GBTV - Where the Truth Lives

Election Season 2014

And it has brought us to this trainwreck called ObamaCare and we have bankrupted our kids and grandkids!

We are now headed into the 2014 Election Season and common sense and conservatism are on the rise. Please stand-up and be counted!

Reading Collusion: How the Media Stole the 2012 Election is a great place to start!

The Founding Father's Real Reason for the Second Amendment

And remember the words of Thomas Jefferson "The strongest reason for the people to retain the right to keep and bear arms is, as a last resort, to protect themselves against tyranny in government." See Video of Suzanna Gratia-Hupp’s Congressional Testimony: What the Second Amendment is REALLY For, below (u-tube HERE).

The Leaders Are Here... Palin, Cruz, Lee, Paul, Chaffetz....

T'S A WONDERFUL LIFE

Can You Really Still Believe That None of These People Would Have Done a Better Job???

Bloggers' Rights at EFF

SIGN THE PETITION TODAY...

Showing posts with label Ben Bernanke. Show all posts

Friday, January 13, 2012

Audit of the Federal Reserve Reveals $16 Trillion in Secret Bailouts

This gives a new meaning to " gov’t. corruption"!!!!

No wonder they didn't want to be Audited..

Audit of the Federal Reserve Reveals $16 Trillion in Secret Bailouts - unelected.org - Click: The Silver Bear Cafe
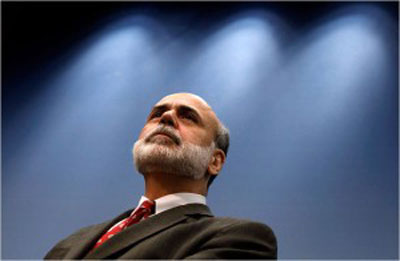
The first ever GAO (Government Accountability Office) audit of the Federal Reserve was carried out in the past few months due to the Ron Paul, Alan Grayson Amendment to the Dodd-Frank bill, which passed last year. Jim DeMint, a Republican Senator, and Bernie Sanders, an independent Senator, led the charge for a Federal Reserve audit in the Senate, but watered down the original language of the house bill (HR1207), so that a complete audit would not be carried out. Ben Bernanke(pictured to the right), Alan Greenspan, and various other bankers vehemently opposed the audit and lied to Congress about the effects an audit would have on markets. Nevertheless, the results of the first audit in the Federal Reserve’s nearly 100 year history were posted on Senator Sander’s webpage earlier this morning.

What was revealed in the audit was startling:

$16,000,000,000,000.00 had been secretly given out to US banks and corporations and foreign banks everywhere from France to Scotland. From the period between December 2007 and June 2010, the Federal Reserve had secretly bailed out many of the world’s banks, corporations, and governments. The Federal Reserve likes to refer to these secret bailouts as an all-inclusive loan program, but virtually none of the money has been returned and it was loaned out at 0% interest. Why the Federal Reserve had never been public about this or even informed the United States Congress about the $16 trillion dollar bailout is obvious - the American public would have been outraged to find out that the Federal Reserve bailed out foreign banks while Americans were struggling to find jobs.

To place $16 trillion into perspective, remember that GDP of the United States is only $14.12 trillion. The entire national debt of the United States government spanning its 200+ year history is "only" $14.5 trillion. The budget that is being debated so heavily in Congress and the Senate is "only" $3.5 trillion. Take all of the outrage and debate over the $1.5 trillion deficit into consideration, and swallow this Red pill: There was no debate about whether $16,000,000,000,000 would be given to failing banks and failing corporations around the world.

In late 2008, the TARP Bailout bill was passed and loans of $800 billion were given to failing banks and companies. That was a blatant lie considering the fact that Goldman Sachs alone received 814 billion dollars. As is turns out, the Federal Reserve donated $2.5 trillion to Citigroup, while Morgan Stanley received $2.04 trillion. The Royal Bank of Scotland and Deutsche Bank, a German bank, split about a trillion and numerous other banks received hefty chunks of the $16 trillion.

"This is a clear case of socialism for the rich and rugged, you’re-on-your-own individualism for everyone else." - Bernie Sanders (I-VT)

When you have conservative Republican stalwarts like Jim DeMint(R-SC) and Ron Paul(R-TX) as well as self identified Democratic socialists like Bernie Sanders all fighting against the Federal Reserve, you know that it is no longer an issue of Right versus Left. When you have every single member of the Republican Party in Congress and progressive Congressmen like Dennis Kucinich sponsoring a bill to audit the Federal Reserve, you realize that the Federal Reserve is an entity onto itself, which has no oversight and no accountability.

Americans should be swelled with anger and outrage at the abysmal state of affairs when an unelected group of bankers can create money out of thin air and give it out to megabanks and super-corporations like Halloween candy. If the Federal Reserve and the bankers who control it believe that they can continue to devalue the savings of Americans and continue to destroy the US economy, they will have to face the realization that their trillion dollar printing presses will eventually plunder the world economy.

The list of institutions that received the most money from the Federal Reserve can be found on page 131 of the GAO Audit and are as follows..

Citigroup: $2.5 trillion ($2,500,000,000,000)
Morgan Stanley: $2.04 trillion ($2,040,000,000,000)
Merrill Lynch: $1.949 trillion ($1,949,000,000,000)
Bank of America: $1.344 trillion ($1,344,000,000,000)
Barclays PLC (United Kingdom): $868 billion ($868,000,000,000)
Bear Sterns: $853 billion ($853,000,000,000)
Goldman Sachs: $814 billion ($814,000,000,000)
Royal Bank of Scotland (UK): $541 billion ($541,000,000,000)
JP Morgan Chase: $391 billion ($391,000,000,000)
Deutsche Bank (Germany): $354 billion ($354,000,000,000)
UBS (Switzerland): $287 billion ($287,000,000,000)
Credit Suisse (Switzerland): $262 billion ($262,000,000,000)
Lehman Brothers: $183 billion ($183,000,000,000)
Bank of Scotland (United Kingdom): $181 billion ($181,000,000,000)
BNP Paribas (France): $175 billion ($175,000,000,000)
and many many more including banks in Belgium of all places

View the 266-page GAO audit of the Federal Reserve(July 21st, 2011): http://www.scribd.com/doc/60553686/GAO-Fed-Investigation

Source: http://www.gao.gov/products/GAO-11-696
FULL PDF on GAO server: http://www.gao.gov/new.items/d11696.pdf
Senator Sander’s Article: http://sanders.senate.gov/newsroom/news/?id=9e2a4ea8-6e73-4be2-a753-62060dcbb3c3

Source: unelected.org  - Click: The Silver Bear Cafe

(The Motto of the Silver Bear Cafe is: "Serving up a heaping helping of the Truth, with a generous side of Common Sense")

Thursday, August 4, 2011

Drunken Ben Bernanke Tells Everyone At Neighborhood Bar How Screwed U.S. Economy Really Is

Bit of a language alert…

The intoxicated Federal Reserve chairman informs bar patrons of the dangers of reckless spending.

SEWARD, NE — Claiming he wasn't afraid to let everyone in attendance know about "the real mess we're in," Federal Reserve chairman Ben Bernanke reportedly got drunk Tuesday and told everyone at Elwood's Corner Tavern about how absolutely ‘fucked’ the U.S. economy actually is.

Bernanke, who sources confirmed was "totally sloshed," arrived at the drinking establishment at approximately 5:30 p.m., ensconced himself upon a bar stool, and consumed several bottles of Miller High Life and a half-dozen shots of whiskey while loudly proclaiming to any patron who would listen that the economic outlook was "pretty goddamned awful if you want the God's honest truth."

"Look, they don't want anyone except for the Washington, D.C. bigwigs to know how bad shit really is," said Bernanke, slurring his words as he spoke. "Mounting debt exacerbated—and not relieved—by unchecked consumption, spiraling interest rates, and the grim realities of an inevitable worldwide energy crisis are projected to leave our entire economy in the shitter for, like, a generation, man, I'm telling you."

A drunken Bernanke attempts to find the Aerosmith song "Back In The Saddle" on the bar jukebox.

"And hell, as long as we're being honest, I might as well tell you that a truer estimate of the U.S. unemployment rate is actually up around 16 percent, with a 0.7 percent annual rate of economic growth if we're lucky—if we're lucky," continued Bernanke, nearly knocking a full beer over while gesturing with his hands. "Of course, if everybody knew that, it would likely cripple financial markets across the entire fucking globe, even in various emerging economies with self- sustaining growth."

After launching into an extended 45-minute diatribe about shortsighted moves by "those bastards in Congress" that could potentially exacerbate the nation's already deeply troublesome budget imbalance, the Federal Reserve chairman reportedly bought a round of tequila shots for two customers he had just met who were seated on either side of him, announcing, "I love these guys."

Numerous bar patrons slowly nodded in agreement as Bernanke went on to suggest the United States could pass three or four more stimulus packages and "it wouldn't even matter."

"You think that's going to create long-term economic growth, let alone promote job creation?" Bernanke said. "We're way beyond that, my friend. There are no jobs, okay? There's nothing. I think that calls for another drink, don't you?"

While using beer bottles and pretzel sticks in an attempt to explain to the bartender the importance of infusing $650 billion into the bond market, the inebriated Fed chairman nearly fell off his stool and had to be held up by the patron sitting next to him.

Another bar-goer confirmed Bernanke stood about 2 inches from her face and sprayed her with saliva, claiming inflation was going to "totally screw" consumer confidence and then asking if he could bum a smoke.

"Sure, we could hold down long-term interest rates and pursue a program of quantitative easing, but c'mon, we all know that's not going to make the slightest bit of difference when it comes to output, demand, or employment," Bernanke said before being told to "try to keep [his] voice down" by the bartender. "And trust me, with the value of the U.S. dollar in the toilet, import costs going through the roof, and numerous world governments unprepared for their own substantial debt burdens, shit's not looking too good for us abroad, either."

"God, I'm so wasted," added Bernanke, resting his head on the bar.

Later in the evening, Richard Kampman, a truck driver who was laid off in 2010, said Bernanke approached him in the men's restroom and attempted to strike up a conversation about various factors contributing to the current financial crisis.

"He stumbled up to the urinal and started mumbling on about the depressed housing sector or something," said Kampman, who claimed Bernanke had to use both hands on the wall to steady himself. "Then after a while he just sort of stopped and I couldn't tell if he was laughing or crying."

"Then he puked all over the sink and the mirror," Kampman added.

Customers at the bar told reporters the "shitfaced" and disruptive Bernanke refused to pay for his drinks with U.S. currency, claiming it was "worthless." Witnesses also confirmed that near the end of the evening, Bernanke put money into the jukebox and selected Dire Straits' "Money For Nothing" to play five times in a row.

"This is what it's all about," said Bernanke, who reportedly danced alone in the middle of the dark tavern. "Fucking love this song."

Source:  The Onion  -  AUGUST 3, 2011 | ISSUE 47•31

Related:

Dow Falls Through the Floor at the Opening Bell

Lieberman Says We Need to Cut Social Security to Pay for Defense 

(Send This Letter to Your Congressman and Senator)

Government Losses to Top $1 Billion After Congress Fails to Reach Deal on FAA

Taxpayers Will Pay for Obama Bus Tour of Battleground States, Says White House

Simpletons Shocked to See Debt Deal Had No Impact on Anything

Scenes from Obamaville's Malaise

Videos:

"Work Being Suspended Involving Tens Of Thousands Of Construction Workers..." Pres Obama -  August 03, 2011 News Corp

We're Losing 200 Million Dollars A WEEK! With The FFA Shutdown - August 03, 2011 CNBC

Massive Hacking Attack Hits U.S. & U.N. Speculation That China Is Involved - August 03, 2011 CNN

"There's No Reason To Blame Us! THEY'RE CRAZY!" Senator Hatch - August 03, 2011 CNN

Are Sarah Palin & Donald Trump The Answer To The Country's Problems? - August 03, 2011 CNN

Tuesday, December 15, 2009

Fat Cats

President Obama stated in his interview on 60 Minutes last Sunday that “I didn’t run for President to be controlled by the Fat Cat Bankers who just don’t get it!” Hmmm… Fat Cats… Fat Cat Bankers… When you look up Fat Cats you find the definition of people like George Soros and Andy Stern… Hmmm the people who financed this campaign, pull his strings and visit the White House regularly. Odd isn’t it??

Fat Cats in the Obama Administration

Obama Slams "Fat Cat" Bankers In 60 Minutes Interview

Various heads of American banks will be heading to the White House on Monday to discuss lending and pay, and it would seem that their host -- the President -- is none to happy with them.

CBS News: In an interview with "60 Minutes" correspondent Steve Kroft, the president went after what he called the "fat cat bankers on Wall Street." He said bankers have not shown "a lot of shame" about their behavior and outsized compensation despite the bank bailouts and economic downturn.

After stating that the financial crisis was "caused in part by completely irresponsible actions on Wall Street," Mr. Obama suggested that some banks paid TARP bailout money back to the government specifically to free themselves from government-mandated constraints on executive compensation.

"I think in some cases that was a motivation," said Mr. Obama. "Which I think tells me that the people on Wall Street still don't get it. They don't get it. They're still puzzled, why is it that people are mad at the banks?"


Watch CBS News Videos Online

Wednesday, December 2, 2009

The United States of Wusses

Posted Dec 01, 2009 02:03pm EST by Henry Blodget

From The Business Insider, Dec. 1, 2009:

When Dubai wobbled last week, everyone rushed to the Internet to await confirmation of the imminent bailout.

And they saw what they wanted to see!

The airwaves (and pipes) were clogged by a steady stream of pundits declaring that there was no way Abu Dhabi would let Dubai go bust.

Why not?

Because if Dubai went bust, then... well... then the stock market might go down for a while! Then the idiots who loaned Dubai World money to build huge islands and buildings in the desert would have to pay for their stupidity! Then the buildings' ownership would change in a debt restructuring--the kind that happens every day in a normally functioning capitalist economy!

INCONCEIVABLE!!!

Remarkably, against this tidal wave of panic and entitlement, Abu Dhabi stood its ground, refusing to reward idiocy by throwing more good money after bad.

And lo and behold... the world's stock markets have stabilized and Dubai is having civilized conversations with its lenders, the same way folks who have had to restructure their debts have had since the dawn of time.

In the United States, meanwhile, Messrs. Bernanke and Geithner no longer have to assure us that they will never let a big bank fail--because we understand that this guarantee has basically been written into the United States constitution. The LESSON OF LEHMAN BROTHERS has been learned, and the lesson is this:

We have become a nation of mamma's boys.

Specifically, after 25 years of debt-fueled consumerism, we have become accustomed to instant gratification and instant fixes, led by politicians and regulators terrified of having to tell us the harsh truth:

We lost our discipline. Getting it back will make life tougher for a while. But it will make us stronger in the end.

It wasn't always this way. In fact, the era of prosperity that we've just enjoyed was made possible by a leader with a huge spine--one who, unlike our current financial and economic leaders, wasn't afraid to risk his job (and enormous public pressure and disapproval) to do the right thing.

Who was that leader?

Paul Volcker.

How much public hatred was Volcker willing to withstand to get us back on the right track?

Take a look at the chart below. The red bars are the Fed Funds rate (which Volcker directly controlled). The blue line is unemployment (which he indirectly controlled).

In 1980, with the country beset by chronic, runaway inflation, Paul Volcker decided to do something about it. Specifically, he hiked rates sharply, into a weak economy.

What happened?

He killed the economy.

Unemployment soared--spiking from 6% to well over 10%, the highest level since the Great Depression. The economy crashed back down into a double-dip recession. Millions of Americans were put out of work. The stock market plunged to 15 year lows.

But Paul Volcker held fast. And a few years later, inflation was all but dead, setting us up for two decades of prosperity (and one of letting ourselves go to pot).

Fast forward to today. Today, we are led by men like Ben Bernanke and Tim Geithner. Men who are so afraid of the consequences of making people pay for their profligacy and stupidity that they have restarted the debt bubble (free money and bailouts for Wall Street, FHA, cash for clunkers) and made Too Big To Fail a national policy.

Take another look at that chart.

Do you think Ben Bernanke would be willing to withstand the heat that Paul Volcker took to get this country back on track? Tim Geithner? Larry Summers? Barack Obama? Do you think any of them would be willing to stand up and deliver the message this country--and Wall Street--desperately needs to hear?

We don't either.

But at some level, we can't say we blame them. Given our current national attitude, we would fire them instantly for even daring to suggest such a thing.

But we'd still be better off hearing it. And it would make us stronger and better in the end.

This is what we all should be like!!

More coverage from The Business Insider:

Tuesday, October 13, 2009

Dollar loses reserve status to yen & euro

Ben Bernanke's dollar crisis went into a wider mode yesterday as the greenback was shockingly upstaged by the euro and yen, both of which can lay claim to the world title as the currency favored by central banks as their reserve currency.

Over the last three months, banks put 63 percent of their new cash into euros and yen -- not the greenbacks -- a nearly complete reversal of the dollar's onetime dominance for reserves, according to Barclays Capital. The dollar's share of new cash in the central banks was down to 37 percent -- compared with two-thirds a decade ago.

Fed boss Ben Bernanke may be forced to raise rates in order to restore faith in the dollar — and help bring the euro and the yen back to earth.

GETTY IMAGES

Fed boss Ben Bernanke may be forced to raise rates in order to restore faith in the dollar — and help bring the euro and the yen back to earth.

Currently, dollars account for about 62 percent of the currency reserve at central banks -- the lowest on record, said the International Monetary Fund.

Bernanke could go down in economic history as the man who killed the greenback on the operating table.

After printing up trillions of new dollars and new bonds to stimulate the US economy, the Federal Reserve chief is now boxed into a corner battling two separate monsters that could devour the economy -- ravenous inflation on one hand, and a perilous recession on the other.

"He's in a crisis worse than the meltdown ever was," said Peter Schiff, president of Euro Pacific Capital. "I fear that he could be the Fed chairman who brought down the whole thing."

Investors and central banks are snubbing dollars because the greenback is kept too weak by zero interest rates and a flood of greenbacks in the global economy.

They grumble that they've loaned the US record amounts to cover its mounting debt, but are getting paid back by a currency that's worth 10 percent less in the past three months alone. In a decade, it's down nearly one-third.

Yesterday, the dollar had a mixed performance, falling slightly against the British pound to $1.5801 from $1.5846 Friday, but rising against the euro to $1.4779 from $1.4709 and against the yen to 89.85 yen from 89.78.

Economists believe the market rebellion against the dollar will spread until Bernanke starts raising interest rates from around zero to the high single digits, and pulls back the flood of currency spewed from US printing presses.

"That's a cure, but it's also going to stifle any US economic growth," said Schiff. "The economy is addicted to the cheap interest and liquidity."

Economists warn that a jump in rates will clobber stocks and cripple the already stalled housing market.

"Bernanke's other choice is to keep rates at zero, print even more money and sell more debt, but we'll see triple-digit inflation that could collapse the economy as we know it.

"The stimulus is what's toxic -- we're poisoning ourselves and the global economy with it."

Comments:

Sorry guys, but you Americans just don’t get it. Your notion of the “fed” still is off? Greenspan, Rockefeller and all the other corrupt guys made you get to ands tay where you are...
If you think it was Obama, regardless of whatever else is wrong with him, then you are still narrow minded un-intellectual stereotypical Americans. Going blind thru decades of being used and now after only 10-months of Obama it should be all his fault.
On this newspaper I thought i would find more interesting comments but i see that the USA/fed republic is still blinded.

I feel sorry for you guys. The world is changing and the problem is not republican or democratic... its that the USA/ America who cannot believe that its not cool anymore to be American and all the other world is not using stars and stripes on t-shirts anymore. How awful the rest of the world is making their own game without the USA; step by step. It started with the euro and will end with a weak dollar.

Doesn’t the CIA report that the weak dollar is the biggest terror fear for the USA?

Its a matter of time till the last guy will see it on the dollar currency.

Cry load America. nobody cares out there. Its time to get rid of American terrorist governments including their war politics.

You need to change… And you need to look at the Fed, Bernanke, Greenspan, the Rockefellers, Gaithner… all of them. Wake-up of parish!

Comment on Whodunit? -

1. Any time that there is something very fishy going on in the financial world, you can bet that George Soros - son of satan - has his dirty rich hand in it. After all, he financed Obama's campaign and paid billions to ACORN, SEIU and other organizations to help get Obama elected. Soros also was most likely behind the 2008 financial crisis. He did the same thing in England a few years ago.
Remember that McCain was ahead in the polls before that happened? Rahm "dead fish" Emanuel even says, "can't let a good crisis go to waste."

2. If what you have surmised about the gold traders is true, sounds like they are more likely gold TRAITORS to America. Add them to the heavy list of traitors to our nation - including the current bogus POTUS, Congress, The Supreme Court, and the courts throughout the land who refuse to take the Obama ineligibility lawsuits to trial.

Apparently, money talks. If that doesn't work, them Obama thuggery takes over the task.

God help our nation - only He can rescue us from the Marxist tyranny being inflicted upon us by our current gangster government.

Source: The New York Post

Related Resources:

Whodunit? Sneak attack on U.S. Dollar – Updated

The G-7 Abandons the Dollar

Making the Connections Part II – History is Important for our Future… Knowing the Underlying Truth is Even More Important

The True Story of the Bilderberg Group

Congressmen Grayson and Paul Ask Senate Banking to Delay Confirmation of Bernanke Until Fed Releases Information – Perhaps Too Late!!

Will a Basket of Currencies Replace the Dollar or Will It be the IMF’s SDR?

Societies move in cycles…

They move from Bondage to Spiritual Faith

From Spiritual Faith to Great Courage

From Great Courage to Liberty

From Liberty to Abundance

From Abundance to Complacency

From Complacency to Dependence – this is where we are now

From Dependence Back to Bondage

The only way to stop this is -

go back to our churches and synagogues and find our Spiritual Faith

Muster up some Courage

Take back our Liberty and rights

And fight to regain our Abundance…

Charles Payne: Stimulus Plan is Distribution of Wealth Plan – Video

Stimulus Money Being Saved for JUST BEFORE 2010 Elections (to put one over on us again) - video

America for Sale: Fighting the New World Order, Surviving a Global Depression, and Preserving USA Sovereignty

Go to www.usdebtclock.org/ – The U.S. Debt Clock

Thursday, October 1, 2009

13 Trillion Missing – Audit the Fed - Updated

Campaign for Liberty

Dear Friend of Liberty,

I hope you join me in my firm conviction that now is the time to fight back against the out of control Federal Reserve and continued Wall Street plundering of our tax dollars.

The threat isn’t hard to see -- just look all around us. Our constitutional principles and freedoms are being assaulted at every turn. More bailouts, trillion dollar “stimulus” plans, huge new debt burdens for our children, simply printing money to cover our failed policies -- I could go on and on. You and I both know that President Obama is going to keep going and going unless someone puts a stop to the madness.

But the good news is there is a way to fight back. And that fight starts today -- by “Auditing the Fed” and showing the American people just how the Fed has abused its power, debauched the dollar, and helped strangle our economy.

Because I know you are a friend in Liberty, I wanted you to be among the first people contacted by Campaign for Liberty for the vital fight against the out of control Federal Reserve.

Please read the enclosed letter from my friend and Campaign for Liberty’s President, John Tate. John isn’t just a friend of mine. He’s also a patriot with years of experience getting things done in politics. Now he’s agreed to take up the fight in a way I cannot -- by leading the fight for Liberty on the outside, while I do battle in the halls of Congress.

I trust you’ll find this battle to expose the out of control Fed worth your support.

For Liberty,
Campaign for Liberty
Congressman Ron Paul

Campaign for Liberty


Trillions of dollars are being stolen from the U.S. taxpayer.
Right now, you and I are seeing the worst plundering of a country’s wealth in the history of civilization, led by an out of control Federal Reserve.

But together you and I CAN put a stop to it all.

With your help (including submitting the petition linked below to your Congressman and Senators) today, Representative Ron Paul, Senator Jim DeMint and Campaign for Liberty are ready to fight back, by taking the battle straight to the heart of the problem – the Federal Reserve itself.

Just think about the scope of the problem for a minute: The massive, outrageous amount of dollars committed to the economic bailouts in recent months totals:

More than the socialist New Deal ... More than the entire Iraq debacle ... More than the 1980’s savings and loan mess ... More than the Korean War ... COMBINED.

When will it all end?

It’s time you and I put a stop to a renegade Federal Reserve by exposing the Fed's out of control actions to the American people. And Congressman Ron Paul and Senator Jim DeMint have a bill before Congress to do just that, known as the "Audit the Fed" Bill (HR 1207 and S 604).

That’s why it’s vital you click here to submit your “Audit the Fed” petition in support of Congressman Paul’s bill.

You see, Audit the Fed already has almost 300 cosponsors!
Now is the time to make sure your Congressman and Senators feel the heat to support the Audit the Fed bill!

If you and I don’t act today, I’m afraid this crisis will end with the economic ruin of every man, woman and child in America.

Today, nearly 13 TRILLION in taxpayer dollars in bailouts and loans has been agreed to by Congress, the Bush and Obama Treasury Departments, and the out of control Fed.

So is it really any wonder more and more folks are starting to realize the Washington, D.C. establishment is hurtling us toward complete economic disaster?

Whether it’s watching a phony “stimulus” package get rammed into law or watching Congress pass a $700 BILLION bank “bailout” under threat of martial law, the American people are agitated and increasingly angry.

That means it’s a perfect time to unleash the pressure of MILLIONS of outraged Americans on the out of control Fed!

So please click here to sign the petition linked below urging your Congressman and Senators to cosponsor and seek roll call votes to pass the Audit the Fed Bill!

As I know you’re aware, the Federal Reserve is shrouded in secrecy. Their meetings are off-limits to the public. Their inner workings are off-limits to the public.

And just recently, the Federal Reserve told Congress “NO WAY” when asked to account for $2 TRILLION in taxpayer-backed loans!

Well, why do you think they refused?

They know coming clean with Congress and the American people on how they doled out that two TRILLION dollars would result in an anti-Fed firestorm.

So can you imagine the impact of a full-scale audit? You and I will finally be able to show the American people that the Federal Reserve System leads to:

*** Constant economic crises -- the housing crisis and the resulting chaos is just one example of an economic bubble created by centrally-planned interest rates and money manipulation;

*** The destruction of the middle class -- as fuel, food, housing, medical care and education costs soar, everyone who is NOT on the government dole is forced to make do with less as the value of their money slowly decreases;

*** Currency destruction -- history shows us that riots, violence and full-scale police states can result when people finally realize our money isn’t worth the paper it’s printed on and REFUSE to accept it.

And unless you and I do end the madness in Washington, D.C., we may be closer than we’d like to think to learning that history lesson firsthand -- right here in our own streets.
That’s why your commitment to helping pass the Audit the Fed Bill –- and helping Campaign for Liberty fight this battle -- is so vital.

Just a few months ago, there was no chance of passing any legislation like the Audit the Fed Bill. So I guess there has been one “CHANGE.”

You see, with the piling up of trillions of dollars in out of control “bailouts” of Wall Street and international bankers, even many politicians in Washington want to show you they’re “being responsible.”

What better way for Congress to do this than by auditing the Federal Reserve to account for the trillions stolen from the U.S. taxpayers?

More and more Congressmen are already feeling the pressure and are signing up to support this bill. I’ve even received word this bill could move in the next few weeks in the U.S. House.

When that happens, you and I must be ready to fight.
And, it’s both a bill we CAN pass, and one that is vital to exposing the massive corruption and dollar manipulation at the Federal Reserve.

You see, after regulating, taxing, spending, borrowing and printing us into what looks like the worst recession in decades, establishment politicians and power brokers are assuring us they’re working hard to “fix” our economic woes. What is their solution? You guessed it. More of the same!

And even if the Audit the Fed Bill is defeated this time, just forcing a vote is a win/win situation.

Can you imagine how many politicians will pay the price at the ballot box in 2010 when you and I tell the American people their Congressman somehow lost trillions of taxpayer dollars and refused to even LOOK for it?

Now we just need to show Congress the American people demand action on the Audit the Fed Bill. Here’s how we plan to do that.
First, we’re already busy contacting up to five million activists nationwide through mail, phones and email to generate petitions to the U.S. Congress demanding action on Ron Paul's Audit the Fed Bill.

But that’s just the beginning. We’ll work the talk radio stations and grant local media interviews to ratchet up the pressure even further on Congress.

And a few days before the vote, if we have the resources, we’d also like to run hard-hitting targeted radio, TV and newspaper ads.

This entire program is designed to send this one, CLEAR message to Congress: Any politician who votes against the Federal Reserve Audit should look for another job.

But such a massive effort won’t be easy -- or cheap.
So in addition to submitting your petition, I also hope you’ll agree to make a contribution of $1000, $500, $250, or $100 to Campaign for Liberty.

If $100 is too much to ask right now, please make a contribution of $50 or even $25 today. Every dollar will help, and every dollar will go to this vital fight.

I know times are hard, but if we don’t take action, the America we see in just a few years could look far worse than even the one we see today.

Can I count on you to join the fight to AUDIT THE FED by clicking here to sign the petition, and by making a generous contribution of $1000, $500, $250, $100, $50 -- or whatever you can afford -- to Ron Paul’s Campaign for Liberty?

Sincerely,

John F. Tate
President

P.S. Please submit the petition urging your Congressman and Senators to cosponsor and seek roll call votes on Rep. Ron Paul's Audit the Fed Bill TODAY!

With Congress spending like never before, and TRILLIONS of new dollars being created out of thin air, it’s never been more important the Federal Reserve’s abuses are exposed to the American people once and for all. And, along with submitting your petition, please make a contribution of $1000, $500, $250, $100, or $50 to Campaign for Liberty TODAY!

---------

In this video commentary, I, Dick Morris, discuss how the United States, at the G20 conference, put itself under the guidance and, ultimately, control of the International Monetary Fund even as it succeeded in turning more power in that organization over to debtor nations. The Declaration of Independence is being repealed before our eyes.


To access the video - Go here!

Tuesday, August 25, 2009

U.S. Raises Estimate for 10-Year Deficit to $9 Trillion as Bernanke – Tapped by Obama to Continue as Fed Chairman??

Congressman John Campbell often shares his opinion(s) with his constituents when he believe the President is doing the wrong thing or when he has new information and updates. Here is today’s update:

Bernanke: As readers of this missive know, I frequently voice my opinion when I believe the President is doing the wrong thing.That has been the case with virtually everything he has done thus far. However, when he takes action that I believe to be correct or helpful, I will point that out as well. Such is the case this week when the President announced that he will reappoint Ben Bernanke as Chairman of the Federal Reserve for another 4 year term. This is a hugely important and very positive decision for the following reasons:

  1. Independence: The Federal Reserve should make decisions for economic reasons and remain independent of the White House so as not to politicize those decisions. I would say this regardless who the President is. Bernanke is independent and will have been appointed by both Bush and Obama. Replacing him could have sent a sign that the Administration was trying to control the Fed which would have been a terrible message and precedent.

  2. Past performance: With the benefit of hindsight, one can criticize some of Bernanke’s moves and statements during his first term. Certainly, he can be criticized for not identifying the depth of last year’s crisis sooner, among other things. But virtually none of us foresaw the severity of the crisis or offered a solution that would have prevented it. Bernanke’s swift and decisive action contributed to saving the economy from what would have been a complete collapse last October. He has done a good job so far and we should let him see the job through back to a normal economy.

  3. Continuity: Markets hate uncertainty, this is particularly true now. Continuing Bernanke’s Chairmanship until January 2014 gives the markets some confidence that monetary policy will be consistent and measured towards the Fed’s mission of growth with low inflation.

  4. No Debt Monetization: This is probably the single most positive sign from the Bernanke reappointment. The federal debt and deficits are huge, unsustainable, and a major risk to future economic growth. Not to mention, it continues to grow. One way to deal with these problems is to “monetize” the debt. That means that the Fed would print money and buy all the new debt issues from the Treasury rather than sell them in the marketplace. Whenever any government has done this on any meaningful scale, it has resulted in uncontrolled inflation and a precipitous decline in the value of the currency. Bernanke has been clear that he thinks this is disastrous economic policy, and he is entirely correct. But it can be a politically easy way out of the mess without raising taxes or cutting spending. But it can’t be accomplished without the Fed Chairman’s 'OK.' Make no mistake; the debt/deficit is still a huge problem. But by reappointing Chairman Bernanke, one of the worst ways to deal with it appears to be off the table. I would also argue that without debt monetization, future inflation prospects are muted somewhat.

I remain respectfully,
Congressman John Campbell's signature
Congressman John Campbell
Member of Congress

----------------

By EDMUND L. ANDREWS – L.A. Times

Published: August 25, 2009

dollar-sign-money WASHINGTON — The Obama administration, citing an economic downturn that has been deeper than it had first thought, raised its estimate on Tuesday of the government’s deficit over the next decade to $9 trillion from $7.1 trillion.

The Office of Management and Budget also said that it expected the economy to contract 2.8 percent this year, substantially more than previously estimated, and that unemployment would peak at around 10 percent.

Even as the new projections cast a shadow over efforts in Washington to steer a middle course between rekindling inflation with too much fiscal and monetary stimulus or risking another recession with too little, President Obama announced that he would nominate Ben S. Bernanke to another four-year term as Fed chairman.

The announcement was made by Mr. Obama while on vacation on the island of Martha’s Vineyard, Massachusetts. It was aimed at maintaining an air of stability in the financial markets as the United States moved toward a recovery credited in part to unprecedented actions by the Fed to help avoid an even worse disaster.

“As an expert on the causes of the Great Depression, I’m sure Ben never imagined that he would be part of a team responsible for preventing another,” Mr. Obama said at a news conference also attended by Mr. Bernanke. “But because of his background, his temperament, his courage, and his creativity, that’s exactly what he has helped to achieve.”

On Wall Street, stocks moved higher in afternoon trading, bolstered not only by the news of Mr. Bernanke’s reappointment, but also by the release of the Case-Shiller home price index, compiled by Standard & Poor’s, which showed that home prices in 18 of 20 top U.S. metropolitan areas were beginning to inch up and new figures showing that consumer confidence had bounded back in August after slipping in July. A Conference Board survey of consumers found that fewer people said that business conditions were bad, and that consumers detected some hints of thaw in the job market.

Despite the budget shortfall, White House officials said they saw no reason to back away from President Obama’s ambitious and costly goal of overhauling the health care system. The new amount includes the cost of the health care overhaul as well as about $600 billion in additional revenue that the administration hopes to raise, two initiatives Congress has yet to approve.

“I know there are going to be some who say that this report proves that we can’t afford health reform,” said Peter R. Orszag, director of the Office of Management and Budget. But he said the opposite was true: the only way to control spiraling Medicare costs, he said, was to get control of overall health care costs by overhauling the system.

“The size of the fiscal gap is precisely why we must enact fiscally well designed health care reform now,” Mr. Orszag said.

Republicans are certain to attack that argument. Indeed, they are already doing so.

Analysts at the Congressional Budget Office put their 10-year deficit estimate slightly lower, at $7.14 trillion, though the agency uses a slightly different method to reach its number. The budget office takes into account only policies already in place, while the administration can consider policies and budget decisions that it hopes to install.

White House officials predicted that the budget deficit this year would peak at $1.58 trillion, though they said the 2009 shortfall would be about $261 billion lower than they had predicted in May. The main reason is that officials have decided that they will not need another round of bailout money for the nation’s banks. The Congressional Budget Official also estimated a deficit this year of about $1.6 trillion.

In the earlier budget forecast, administration officials had created a “placeholder” of $250 billion to cover possible costs of additional bank bailouts. They also assumed higher costs for the Federal Deposit Insurance Corporation’s expansion of deposit insurance and debt guarantees.

Even so, the administration is projecting that annual deficits will remain above $1 trillion through 2011 and will be bigger than any since World War II, even when measured conservatively as a share of the nation’s economic output.

The government’s total debt would roughly triple by 2019, to $17.5 trillion, under the new estimate, almost $2 trillion more than the White House estimated in May. Measured as a share of the nation’s economic output, public debt would hit 76.5 percent of gross domestic product by 2019 — by far the highest percentage in the past half-century — from about 56 percent this fiscal year. This year will be the first time the number has exceeded 50 percent since World War II. The previous estimate was about 67 percent.

The biggest reason for the additional red ink is the administration’s recognition that the recession has been deeper and unemployment has been much higher than White House forecasters assumed in their first budget estimate in May.

The added depth of the downturn is expected to increase payouts for unemployment benefits and other safety-net programs, while reducing tax receipts more than originally expected.

The administration had originally assumed that the economy would shrink 1.2 percent and that unemployment would average about 8.1 percent this year. Instead, the economy is expected to shrink 2.8 percent while unemployment is expected to average 9.3 percent in 2009 and 9.8 percent in 2010. The administration expects growth of 2 percent next year and 3.8 percent in 2011.

In contrast, the Congressional Budget Office expects a 2.5 percent contraction this year, followed by growth of 1.7 percent in 2010 and 3.5 percent in 2011. For the first time, administration officials officially predicted on Tuesday that unemployment would climb above 10 percent by early next year, from 9.4 percent in July.

The costs of the additional unemployment and the slower growth extend beyond the next year or two, not just because the economy will take longer to return to normal but also because the government’s interest expense will be compounding more rapidly.

Mr. Orszag estimated that, by 2019, interest expenses would account for more than 80 percent of the projected deficit of $917 billion.

Without offering any details, the White House budget director said that President Obama would soon unveil plans to reduce long-term deficits tied to soaring costs of Medicare, Social Security and other entitlement programs.

There are only two ways to do that:

1. Finally listen to the American People and Conservatives in Congress and dump Obamacare while over-hauling entitlement programs by attacking Fraud and major Tort Reform

(or)

2. Ration and short-change old people and people with special needs…

For gosh sakes… how long can we really believe that a government who is $2 Trillion off on their debt projection can run anything, let alone efficiently?? Now we should trust them to manage our healthcare, one-sixth of the U.S. Economy…?

Posted: Knowledge Creates Power – Cross Posted: Daily Thought Pad